Showing posts with label Investment Strategy. Show all posts
Showing posts with label Investment Strategy. Show all posts
Tuesday, September 8, 2009
Monday, September 7, 2009
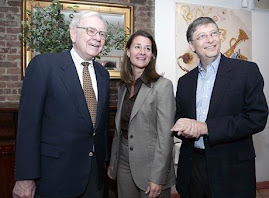
5 Common Warren Buffett Myths Debunked
Somebody posted an interesting article on an investment website about Warren Buffett which I agree in part. Although Warren Buffett has been my role model in investment management, some years ago, I realized that he doesn’t really practise what he preached. For example, he invested in China oil company, junk bonds, currencies etc.
Nonetheless, value investment is still a sound investment approach that works for decades, valid today and for the years to come.
===============================
Berkshire Hathaway (BRKA) recently posted its worst loss ever and the media is buzzing again. This article attempts to clear up some of the most widely portrayed Warren Buffett myths.
Berkshire Hathaway stock, the most expensive stock in the world, peaked at $149.972 in December 2007 and has since fallen at one point over 50% hitting a multi-year low of $70,100 in early March, 2009. BRKA stock today closed at $81,690. Myths below.
1. He buys cheap stocks.
Probably the most common and widespread misconception of Warren Buffett is that he got so wealthy by buying cheap stocks. Though Warren Buffett advocates buying stocks at fair or even firesale prices if possible, it is not the only metric of his decisions. In fact, it may be a relatively minor factor in his considerations.
In his younger years, Buffett bought stocks he called “cigarette butt” stocks. Namely stocks that were selling for attractive prices (i.e. under book value, at a third of working capital etc). He did great but not very great. Buffett later acknowledged that he found out it was much better to buy good businesses instead of just cheap stocks. He later made the bulk of his fortune in American Express, Geico, Coca Cola, Gillette etc.
2. He’s ever wrong.
Yes, even Warren Buffett can be wrong! In the early 1980s, Buffett was worried that hyperinflation would make bonds unattractive investments. But inflation eventually ticked down and hasn’t raised its ugly head yet for nearly 30 years.
Buffett also made mistakes in his stock and bond investments. He bought preferred stocks in an airlines company that almost got wiped out and sold McDonald’s too early. He bought many stocks he later wished he didn’t buy. Most recently, he became the largest institutional shareholder of Conoco Phillips, an oil company, when oil prices were near their highs.
The lesson here is not knocking on Buffett. Instead, realizing that even the Oracle of Omaha can be wrong quite often tells you that losses and being wrong are an inevitable part of investing. The key issue is how we deal with risk and losses, and whether we make a lot more on our winners than we lose on our losers.
3. Buffett doesn’t trade.
Contrary to public opinion, Buffett doesn’t just invest in stocks. Though Buffett frowns on speculation, Buffett does not refrain from making investments in currencies, commodities or even the stock market of a speculative nature. In the early 2000s, Buffett actually shorted the Dollar, tidying up a handsome profit as he covered his positions a few years ago. Buffett has also been involved in silver, copper and oil (as can be seen from his letters to shareholders). Buffett also does arbitrage in the stock market. But he usually controls the sizes of his speculative positions. Perhaps the lesson to be learnt here is only to risk what you can afford to lose if you’re going to speculate.
4. Buffett doesn’t use financial leverage.
This may be one of the most persistent myths about Buffett. Buffett once wrote “Debt is a four letter word.” He strongly preaches against highly leveraged business/financial operations, but in fact, Buffett does use financial leverage. At the start of his investment career, he managed assets for other people. That’s leveraging his knowledge. Later on, Buffett bought insurance companies which generate lots of money from premiums known as “float”. Buffett could invest the float until there were claims from insurees. Though float is low cost compared to the profits Buffett generates from his investments, this is leverage nonetheless.
5. Buffett doesn’t diversify.
This is not true. Berkshire Hathaway owns dozens of companies and has investments in many sectors. True, Buffett says he like concentrating his investments in companies he fully understands. But he also recommends for the investor who doesn’t have much time for investment research that he “believes in extreme diversification”
The Oracle of Omaha is not a god, far from it, but he has many traits and his investment philosophy can be studied and learned from to aid our own personal investment decisions.
Thursday, October 9, 2008
Stock Market Review - Oct 08 (Part 3)
5) HupSteel. This is yet another wonderful company and I am still one of its shareholders. I make capital gain out of it before and bought it again when it retreated. Only that now I stuck with this counter but without regret. This is because HupSteel is still a wonderful company earning some decent return. I remember one of ex-colleagues bought HupSteel in 90s at around $0.70. Back then, HupSteel was known as Hup Seng Huat and my friend got stuck with the company for a very very long time. However, things changed after global economy started to recover in 2004. There was huge demand for metal and HupSteel was riding on solid growth. Its share price went up to $0.60 even after the company issues bonus, rights and giving out good dividend. But today, its share price dropped to $0.215. Let’s take a look on its financial performance and position.
Business: dealer in steel products, hardware and property investment holding company.
Report: FY2008
Revenue: surged to S$433.7m (53% variance)
Net profit: surged to S$45.1m (45% variance)
NP margin: 10.4%
Cash: S$27.4m
Working capital: 2.34
LT debt to total capital: 1.8% (very little)
Basic EPS: 7.33 cents
PE: 2.93
NTA: S$0.3298
Yield: 9.3% (excl special dividend)
Director’s remark: demand for steel product to remain strong and full orderbooks from offshore and marine customers.
My remarks: In my opinion, current price does not reflect on the company financial performance and position – it’s under-priced. But then again, we still need to take cue from US economy. So hold on, stay tune and follow this company closely.
6) Pan United. Pan United just another wonderful company and I made a few buck out of it during recent bull run. In fact, I made money out of its subsidiary, Pan United Marine too. Both are wonderful company with strong profit growth and high dividend yield. Pan United is currently traded at $0.44. Let’s take a look at its financial performance and position.
Report: 1H2008
Revenue: surged to S$135.9m (25% variance)
Net profit: surged to S$14.5m (37% variance)
NP margin: 10.7%
Cash: S$53.3m
Working capital: 1.79
LT debt to total capital: 26.5%
Basic EPS: 4.53 cents
PE: 9.71
NTA: S$0.445
Yield: 4.1% (interim excl special dividend)
Director’s remark: positive outlook for FY2008.
My remarks: Pan United’s business is quite diverse and it’s not easy to analyse. However, the company is still profitable and trading at reasonable price. Worth a second look but no hurry.
..........To be continue
Thursday, October 2, 2008
Stock Market Review - Oct 08 (Part 2)
3) China Sunshine Chemical. Actually I don’t really want to discuss on “red” stocks in this series of stock market review. This is because my confident on China companies has always been low due to their corporate governance and internal control. Now before you jump to conclusion, I must let you know that I have nothing against China nationals. In fact I have close friends from China, I have colleagues from China and I love to visit China. But comes to business, I am really worried. I have friends importing goods from China sharing with me the Chinese’s mindset, attitude and method when dealing with business. I don’t think you want to know or perhaps you already knew. So when these red stocks found their way to the SGX, I seldom apply for their IPOs, let alone talking about investment. Yes I know many have made good money out of it, but that’s not my point. My point is with doubt on their corporate governance and internal control, I dare not invest in China companies.
“How come you have doubt? Can you quantify?”
Read the paper lah, brother! Even if you don’t read Business Times, at least read LianHeWanBao right? And I’m not only talking about current milk powder issue. Notwithstanding my negative thoughts, I am still willing to take some risk on a few really good ones. So here I am going to share with you on China Sunshine Chemical.
Firstly, I did not make any profit from this counter. In fact since the day I invested in it, it did not perform as expected. And right now I am sitting on significant losses instead. Then did I make a mistake in my investment decision? I don’t think so. Besides, there are also other professional analysts drawing the same conclusion. Then what’s the basis of my recommendation back then? Firstly, the company is producing a type of chemical that is essential to make rubber into something like a car tyre. The company is one of the world largest producer supporting many world-renowned tyre manufacturers such as Bridgestone, Michelin, Goodyear, Pirelli etc. Most importantly, this chemical only takes up a small percent of a tyre’s manufacturing costs. And in my opinion, recession or economic boom, people still own car, F1 continue to race, buses and airplanes continue to roll out. China Sunshine Chemical is currently priced at $0.205. What about its recent financial performance and position?
Business: one of the largest rubber accelerator manufacturers in the world and in China in terms of production capacity.
Report: 1H2008
Revenue: surged to Rmb402m (41% variance)
Net profit: surged to Rmb61m (37.3% variance)
NP margin:13.3%
Cash: Rmb37.4m
Working capital: 3.84 (healthy)
LT debt to total capital: 0% (wow!!!)
Basic EPS: Rmb10.89 cents
PE: 9.41
NTA: Rmb1.01
Yield: N.A.
Director’s remark: expect to continue its growth for FY2008.
My remarks: I believe the business, to certain extent, is immune to economic downturn. There may be some impact but should not be severe. The company is currently reasonably priced.
4) Courage Marine. Courage Marine was really one of the last marine companies to perform in terms of share price. This was partly due to the fact that it was a new IPO. But what really caught my attention on this company was its high profit margin. And honestly, I don’t understand why its profit margin is so high. So early last year (2007), in the midst of the bull run, I bought Courage Marine at a very cheap price - $0.19. One year later, I sold it at 100% capital gain, excluding dividends! Actually the dividend payout can be very high if not of its high quantity of outstanding shares. Courage Marine, after recent blood bath, is currently trading at $0.215. What about its recent financial performance and position?
Business: ownership and operation of dry bulk carriers and the provision of marine transportation services.
Report: 1H2008
Revenue: surged to US$50m (43% variance)
Net profit: surged to US$30.3m (51% variance)
NP margin: 60.6%!!!!!!!!
Cash: US$68.6m (fat)
Working capital: 16.5 (OMG! Super healthy)
LT debt to total capital: 0% (OMG!!!)
Basic EPS: US$1.67 cents
PE: 9.19
NTA: US$11.75 cents
Yield: 4.65% (for half year)
Director’s remark: BDI collapsing to 5,600 level (I got no clue what’s a BDI). Company expects demand from China to remain strong and the group to continue to do well in second half.
My remarks: Similarly, if not because of uncertain global economy, I would have started buying Courage Marine.
…….To be continue
Wednesday, October 1, 2008
Stock Market Review - Oct 08 (Part I)
It’s about time we review SGX-listed stocks. We’ll take a look on their current status and look back on its performance few years back. I had spend a few days reviewing all the listed stocks and truth be told, most of them are currently cheaply priced. What do I mean by “cheap”? In 2004, local economy and stock market started to recover. I remember that in mid 2003, I saw the indicators and believed that we are going to bottom up. Before I quit the Army, I told my ex-colleagues that “I think it’s about time”. I launched my first wave on the tech stock/funds. And from 2004 – 2005, many stocks were lagging behind because Ms. Market was shaky; she wasn’t sure. Index was fluctuating without clear direction. As such, I spend considerable amount of time finding gems rather than following “road-runners”. I found quite a lot of it and I’ll share a few with you today. Some of my readers may have followed my recommendation and benefited from it. Appreciate if you can testify here.
In my opinion, right now most of the counters are priced at a level similar to 2005. No doubt still has room to plunge further, but really quite cheap comparatively.
The Index
As expected, STI could not hold its ground since late last year. When sub-prime woes were exposed, STI took a hit in around July 2007. However, in around September 2007, global market under-estimated the damaging power of US financial crisis, it continued to move up. And in around Dec 2007, with surging oil price, global market started to loss steam and it was “neither here or there”. And then I’m sure it’s GAME OVER. Thereafter I started to advise my friend to either hold or sell BUT do not give a single cent to Ms. Market – she is breaking down soon.
(Note: some of you may know that “Mr. Market” is a term used by Warren Buffet and his teacher Benjamin Graham to describe market behaviour. But I used “Ms. Market” instead as I find the market behaved like a girl – temperamental!)
In early January this year, STI was around 3,400 points. As at today, STI stands at 2,361.34. Approximately 1,000 points had been wiped out. So this proves my points that although there will be fluctuations along the way, ups and downs but overall it’s coming down. And unless you speculate, you will not make it if you invest along the way.
This is the downtrend of the business cycle.
Selected Stocks
1) AusGroup. Now this is really one of mine favourite stocks. I (and my all-time favourite analyst, BT Snr Correspondence, CFA Charterholder - Ms Teh Hooi Ling) found the gems before it skyrocketed. Hooi Ling visited AusGroup’s management in Australia and wrote an excellent report published on the paper. The stock was initially priced around $0.30 in 2006. And then it became a rocket surged all the way to around $2 almost non-stopped. And what is its price now? Unbelievable $0.265! What about its recent financial performance and position?
Business: supporting oil & gas industry.
Report: FY2008
Revenue: increased to A378.9m (34.8% variance)
Operating profit: dropped to A21.7m (23.9% variance)
NP: dropped to A14.4m (27.8% variance)
NP margin: 3.8%
Cash: A18.7m
Working capital: 1.61
LT debt to total capital: 28%
Basic EPS: A3.6 cents
PE: 7.36
NTA: A22.5 cents
Yield: 2.3%
Director’s remark: secured higher orders; expected FY2009 to be profitable.
My remarks: margin and yield is unimpressive. Profit may soften further but likely to remain positive. I do not expect oil price to stay below $1 next year. Overall performance and position looks fine.
2) Bonvest Holdings. This is yet another company which make me proud; make me scream. In 2005, Bonvest was a lager and I found this gems. I studied its businesses and strongly believed that it worth more than $0.55. However, Ms. Market has different opinion. So I bought in the share and within that year, I disposed it at $0.905 – too early!!! You must be shocked when I say “too early”. Yes, after I locked in my profit, Bonvest continued to surge to around $1.70!!!!!
“Wow, then you must have regretted and jump!”
No, remember that in investment, your greatest weakness is greed and fear. I’ve earned my money, I moved on. Bonvest is currently priced at $0.72. What about its recent financial performance and position?
Business: property development and investment, food and beverage, hotel ownership and waste management.
Report: 1H2008
Revenue: dropped to S$119.7m (28.1% variance)
Operating profit: surged to S$100m (238.8% variance) due to revaluation gain of $70.3m. Without it, operating profit should be around $30m (about the same as previous identical period)
NP: surged to S$86m for the same reason (266.2% variance)
Cash: S$89.5m (fat)
Working capital: 2.15 (healthy)
LT debt to total capital: 0.26% (extremely low)
Basic EPS: S$20.7 cents
PE: 3.4
NTA: S$1.65
Yield: N.A.
Director’s remark: challenging and competitive market. Minimal contribution expected from most of its business segments.
My remarks: You want to know how I feel now? I feel that there is a very beautiful lady standing right before me, single and available. And luckily you’ve stopped me otherwise I would have jump onto it like right now! I mean if you buy Bonvest now, you are paying S$0.70 for a company that worth S$1.65! Bonvest’s financial position and performance is very impressive although it may not be able to hold its ground in view of intense market competition and uncertain global economy. And that’s exactly why I’m not calling a buy but close monitoring. US economy is highly uncertain couple with high oil and food prices; we are really not sure where this is leading to.
…… To be continue
 I quit the Army, I told my ex-colleagues that “I think it’s about time”. I launched my first wave on the tech stock/funds. And from 2004 – 2005, many stocks were lagging behind because Ms. Market was shaky; she wasn’t sure. Index was fluctuating without clear direction. As such, I spend considerable amount of time finding gems rather than following “road-runners”. I found quite a lot of it and I’ll share a few with you today. Some of my readers may have followed my recommendation and benefited from it. Appreciate if you can testify here.
In my opinion, right now most of the counters are priced at a level similar to 2005. No doubt still has room to plunge further, but really quite cheap comparatively.
The Index
As expected, STI could not hold its ground since late last year. When sub-prime woes were exposed, STI took a hit in around July 2007. However, in around September 2007, global market under-estimated the damaging power of US financial crisis, it continued to move up. And in around Dec 2007, with surging oil price, global market started to loss steam and it was “neither here or there”. And then I’m sure it’s GAME OVER. Thereafter I started to advise my friend to either hold or sell BUT do not give a single cent to Ms. Market – she is breaking down soon.
(Note: some of you may know that “Mr. Market” is a term used by Warren Buffet and his teacher Benjamin Graham to describe market behaviour. But I used “Ms. Market” instead as I find the market behaved like a girl – temperamental!)
In early January this year, STI was around 3,400 points. As at today, STI stands at 2,361.34. Approximately 1,000 points had been wiped out. So this proves my points that although there will be fluctuations along the way, ups and downs but overall it’s coming down. And unless you speculate, you will not make it if you invest along the way.
This is the downtrend of the business cycle.
Selected Stocks
1) AusGroup. Now this is really one of mine favourite stocks. I (and my all-time favourite analyst, BT Snr Correspondence, CFA Charterholder - Ms Teh Hooi Ling) found the gems before it skyrocketed. Hooi Ling visited AusGroup’s management in Australia and wrote an excellent report published on the paper. The stock was initially priced around $0.30 in 2006. And then it became a rocket surged all the way to around $2 almost non-stopped. And what is its price now? Unbelievable $0.265! What about its recent financial performance and position?
Business: supporting oil & gas industry.
Report: FY2008
Revenue: increased to A378.9m (34.8% variance)
Operating profit: dropped to A21.7m (23.9% variance)
NP: dropped to A14.4m (27.8% variance)
NP margin: 3.8%
Cash: A18.7m
Working capital: 1.61
LT debt to total capital: 28%
Basic EPS: A3.6 cents
PE: 7.36
NTA: A22.5 cents
Yield: 2.3%
Director’s remark: secured higher orders; expected FY2009 to be profitable.
My remarks: margin and yield is unimpressive. Profit may soften further but likely to remain positive. I do not expect oil price to stay below $1 next year. Overall performance and position looks fine.
2) Bonvest Holdings. This is yet another company which make me proud; make me scream. In 2005, Bonvest was a lager and I found this gems. I studied its businesses and strongly believed that it worth more than $0.55. However, Ms. Market has different opinion. So I bought in the share and within that year, I disposed it at $0.905 – too early!!! You must be shocked when I say “too early”. Yes, after I locked in my profit, Bonvest continued to surge to around $1.70!!!!!
“Wow, then you must have regretted and jump!”
No, remember that in investment, your greatest weakness is greed and fear. I’ve earned my money, I moved on. Bonvest is currently priced at $0.72. What about its recent financial performance and position?
Business: property development and investment, food and beverage, hotel ownership and waste management.
Report: 1H2008
Revenue: dropped to S$119.7m (28.1% variance)
Operating profit: surged to S$100m (238.8% variance) due to revaluation gain of $70.3m. Without it, operating profit should be around $30m (about the same as previous identical period)
NP: surged to S$86m for the same reason (266.2% variance)
Cash: S$89.5m (fat)
Working capital: 2.15 (healthy)
LT debt to total capital: 0.26% (extremely low)
Basic EPS: S$20.7 cents
PE: 3.4
NTA: S$1.65
Yield: N.A.
Director’s remark: challenging and competitive market. Minimal contribution expected from most of its business segments.
My remarks: You want to know how I feel now? I feel that there is a very beautiful lady standing right before me, single and available. And luckily you’ve stopped me otherwise I would have jump onto it like right now! I mean if you buy Bonvest now, you are paying S$0.70 for a company that worth S$1.65! Bonvest’s financial position and performance is very impressive although it may not be able to hold its ground in view of intense market competition and uncertain global economy. And that’s exactly why I’m not calling a buy but close monitoring. US economy is highly uncertain couple with high oil and food prices; we are really not sure where this is leading to.
…… To be continue
Wednesday, February 27, 2008
Should I Buy Stock Now? (Part I)
Is This The Right Time?
God know! The obvious answer is god know! But yet this is the most frequently asked question from my friends and colleagues. The prices of most companies are quite cheap now as compared to end of last year. For one thing, I am currently sitting on an unrealized loss of approximately S$10,000!!!
“I thought you are a guru?”
Firstly, I never claim that I am a guru; I am still learning. Secondly, even the experts can also bankrupt let alone suffering losses. Let me share a part of the story from the Romance of Three Kingdom ( 三国志 ) with you. After retreating and avoiding Cao Cao’s (曹曹) attack, Zhuge Liang (诸葛亮) finally decided to defeat Cao Cao once and for all at Chang Jiang (长江) – with the help of Dong Wu (东吴). To persuade Sun Quan (孙权) to partner with Liu Bei (刘备) to repel Cao Cao’s forces, Zhuge Liang presented his strategy that guarantees success.
All the ministers contributed their fair share in trying to topple Zhuge Liang's plan. One of the ministers countered his proposal by asking Zhuge Liang – “if you are that good, can you explain why your forces were defeated and escape from Cao Cao’s forces until you reached Jing Zhou (荆州)". To this question, Zhuge Liang answered, “there is never an undefeatable army in this world. Being able to protect our people, to bring them along until we reached Jing Zhou is already a great success paving the road to greater victory. We won the heart of our people; this is the greatest victory".

In the War of Chi Bi (赤壁), Cao Cao lost nearly one million soldiers thus equalized the three forces in the Central. We called it 三国鼎立.
God know! The obvious answer is god know! But yet this is the most frequently asked question from my friends and colleagues. The prices of most companies are quite cheap now as compared to end of last year. For one thing, I am currently sitting on an unrealized loss of approximately S$10,000!!!
“I thought you are a guru?”
Firstly, I never claim that I am a guru; I am still learning. Secondly, even the
 experts can also bankrupt let alone suffering losses. Let me share a part of the story from the Romance of Three Kingdom ( 三国志 ) with you. After retreating and avoiding Cao Cao’s (曹曹) attack, Zhuge Liang (诸葛亮) finally decided to defeat Cao Cao once and for all at Chang Jiang (长江) – with the help of Dong Wu (东吴). To persuade Sun Quan (孙权) to partner with Liu Bei (刘备) to repel Cao Cao’s forces, Zhuge Liang presented his strategy that guarantees success.
All the ministers contributed their fair share in trying to topple Zhuge Liang's plan. One of the ministers countered his proposal by asking Zhuge Liang – “if you are that good, can you explain why your forces were defeated and escape from Cao Cao’s forces until you reached Jing Zhou (荆州)". To this question, Zhuge Liang answered, “there is never an undefeatable army in this world. Being able to protect our people, to bring them along until we reached Jing Zhou is already a great success paving the road to greater victory. We won the heart of our people; this is the greatest victory".

In the War of Chi Bi (赤壁), Cao Cao lost nearly one million soldiers thus equalized the three forces in the Central. We called it 三国鼎立.
.
And lastly, my losses does not affect my daily life at all. In fact I am planning for a holiday next month. Yes I am upset but the loss will not upset my life. The reason is simple - I didn't gamble and the companies I invested in have reasonable fundamental plus yield.
The Threat
I will not beat around the bush. IMHO, the uncertainty in US economy is very real and probability of a recession seems to be getting higher. US consumer confidence is dropping and we just don’t know how deep this subprime problem is. So for anyone who claimed that US recession will not affect us is telling the biggest lie – our products exported mainly to US and Europe. China and India is not big enough (does not have a large stomach) to replace US demand. So how can someone say taht it will not affect us. Economic downturn will cause the stock market to clash which recent correction (since end of 2007) is already bad enough. And I think that it’s about time for the bear to sleep.
And not forgetting that oil price still hovers around $100 mark. One of my friends who is current working in a fund house believes that high oil price is “OK”, i.e. not a concern. I totally disagreed with his views even though he is working in a fund house and I am not. Why? Because I have commonsense. Like my lecture used to say, “commonsense is the least common human attributes. High oil price will increase production that will ultimately pass on to the end consumers. And so the workforce will demand high pay rise to cope with high living costs. And when labour costs went up, businesses will……. The whole chain effect, if uncheck, will finally explode. I mean it has to be.
Reported in Business Times dated 20 Feb 2008, MAS MD Heng Swee Kiat said that a sharp and deep recession in the United States will hit Asian economies. The following is an excerpt of the newspaper report.
"Wading into the debate on whether Asia has de-coupled from the US, Mr Heng said the region has significant links with the world's biggest economy through trade, investment and finance. Only if these linkages are significantly weakened can Asia be said to have de-coupled from the US, he said yesterday at a fund management conference.
Still, the short-term outlook for Asia remains generally positive barring any sharp deterioration in the global economy, he noted. The current forecast is for Asia ex-Japan to grow at a fairly healthy pace of around 7.8 per cent in 2008, one percentage point lower compared to last year."
So Is It The Right Time To Buy Share?
In my opinion, you should shun away from the stock market until the sky is clear. However, personally, I don’t think it is going to be cleared this year. There may be bull-trap but I have no faith that all this economic problems can be completely resolve this year. Having said that, and unfortunately, you also can’t place your spare cash in the bank. I strongly discouraged you from doing so. For many years, local banks have been giving out pathetic interested rates; rates that are below the inflation rate. And now this problem compounded with inflation rate at all time high. Putting large amount of spare cash in whatever bank account will ensure that you suffer a lost in money value.
“I’m still waiting for your recommendation.”
I propose three options to maximized your returns:
1) Pay up whatever debts you have as much as possible. In times of high inflation, where money value eroded, clear your debts with all your spare cash unless you know of alternative investments that yield even higher returns with calculated risk. For example, try to pay up your car loans or housing loan as much as possible if the financial company allows you to do so. Let your creditors deal with the high inflation problem.
2) Transfer your spare cash into the CPF. Thereafter, you can
 move some money from the Ordinary account to the Special account. The Special account gives out at least 4% rate currently and is meant for retirement planning. However, remember that by doing so, your spare cash will be locked up in the CPF.
3) Buy high yield and fundamental stocks but this requires strategy. Although the stock market is quite risky now, there are still a few fundamental stocks that give out good and presumably stable dividends yield. One such group of companies is the REITs.
In my next sharing, we will look at some of the REITs that look attractive. Before I close, just to give you a hind, Suntec REITs looks attractive to me.

Tuesday, November 27, 2007
Monkey-See-Monkey-Do Strategy
Follow The Experts
Does following experts blindly yield lucrative returns, or even beat the index? I remember some time last year (or the year before), there was article in the Business Times reporting that local investors enjoy high returns by simply following behind Temasek Holding's investment actions. According to the report, whenever Temasek invested in a listed company, you just follow, no question asked. At the end you still make relatively high returns (I don’t have the figure with me, need to find that article). Some of you may be able to recall such article.
So is monkey-see-monkey-do strategy works? In my opinion, it definitely will as long as:
1) You do not speculate
2) You follow, even blindly but the correct experts
Point 1) above is important because if you speculates and try to follow blindly, in my opinion, you will end up contributing to the “experts” you followed. But for value investment, which takes time to yield the expected result, it’s ok if you follow the right experts.
On 17 Nov 2007, there was a wonderful article on the Business Times further reinforce that monkey-see-monkey-do strategy does work – if you follow Mr Warren Buffett. When Warren Buffett bought PetroChina in 2003, my course mates and myself were aware of it and wanted to follow him. So what’s stopping me?
1) After Warren Buffett’s investment in PetroChina, its share price surged a bit….I was unhappy about it.
2) To buy Hong Kong stock, which I am not really familiar with, I will incur custodian fees. I don’t really like the additional cost especially when I am not buying large quantity.
Unfortunately, I was wrong. Warren Buffett makes big bucks from PetroChina. And if I followed blindly behind him, I am sure I will also make that kind of money. So we can use monkey-see-monkey-do strategy but do intelligently; at least follow the right experts.
The following is an excerpt of the article in Business Times. Enjoy.
========================================
Business Times - 17 Nov 2007
Even a monkey can get 24% with this investment formula
Investors could beat the S&P 500 just by imitating Warren Buffett's trades
(NEW YORK) Buying whatever billionaire Warren Buffett bought, often months after his share purchases, delivered twice the return of the Standard & Poor's 500 Index during the past three decades.
Investors would have earned an annual return of 24.6 per cent by buying the same stocks as Mr Buffett after he disclosed his holdings in regulatory filings, sometimes four months later, according to a soon-to-be-released study by Gerald Martin of American University in Washington and John Puthenpurackal of the University of Nevada, Las Vegas.
The S&P 500 rose 12.8 per cent a year in the same period.
'A monkey would have beaten the pants off the S&P 500 by following Warren's buying and selling,' said Mohnish Pabrai, who manages US$600 million at Pabrai Investment Funds in Irvine, California.
Mr Pabrai and a friend paid US$650,100 this year in an annual charity auction to lunch with the 77-year-old Buffett.
Mr Buffett's stock picks outperformed his Omaha, Nebraska-based Berkshire Hathaway Inc from 2002 to 2006 when Berkshire shares advanced at a yearly rate of 7.8 per cent.
By comparison, Berkshire holding USG Corp, the biggest maker of gypsum wallboard in North America, increased about 1,140 per cent and PetroChina Co, China's largest oil producer, soared eight-fold.
Mr Buffett built Berkshire Hathaway during the past four decades into a US$200 billion company with businesses ranging from ice cream and bricks to insurance and corporate jet leasing.
Berkshire had US$77.9 billion invested in stocks at the end of September, according to a filing with the US Securities and Exchange Commission.
The company's shares closed on Thursday at US$135,300, the highest price on the New York Stock Exchange.
Monday, November 5, 2007
Investment Strategy - Surviving The Economic Downturn (Final)
In Part I of this topic, I mentioned that generally, investment in bonds should come with capital protection. This is because in any worst-case scenario, you will get back your capital at par value. But company can fold up especially in bad times. If you invest in a bond directly, you will know its characteristics including risk. But if you buy bond funds, you got to be careful. The fund brochure may use big words such as “secure”, “capital protection” etc. But you should really read the fine print usually right at the bottom. It will say something like “the fund may incur losses if any borrower defaulted or “capital protection is only guaranteed assuming no default” etc. The reason is because fund manager may buy corporate bonds which come with higher risk. And if one of the companies default on its obligation, your bond fund will suffer and the price will fall. Of course if the bond fund's policy statement clearly states that the fund only invest in “AAA” investment grade bonds (especially government bonds), then the comfort of “capital protection” will be much higher.
So what will happen if a company (the borrower) defaulted or fold up? If the company defaulted, the trustee will demand the money back immediately. This may cause the bank and all other borrowers to do the same so as to protect their interest. Then the company’s fate may become a self-fulfilled prophecy due to cashflow problems.
What if the company fold up? The good news is that bondholders are the first “claimer” when the company liquidates. The company’s remaining assets will be sold off, cash realised will be use to pay back the bank and bondholders first. These lenders are on top of the list.
So Is That All?
Unfortunately, no! So we know that the best time to buy bond is when interest rate is high, when the business cycle is around the peak, when there are enough evidence to believe that the bull run is unsustainable. The biggest problem is – how do you define “high”? How do you know if a downturn is coming? How do you know that US will ignite a recession in 2008? Didn’t George Soros predicts a recession this year? How about asking the economists? Well, if the economists is that good, how come he/she is still earning employment income? By the way, I thought only God knows the future? Imagine if I followed some analysts’ prediction and dispose off all my shares last year, I’ll be crying now. This year, global stock markets are bullish setting one record after another even in the midst of rising oil price and US subprime woes. If you ask if I have any clue, I have no clue. Yes, the best thing anyone including any expert can do is only to analyse, assess and to come up with his/her BEST GUESS.
My recommendation is this:
1) Do your homework, make your best guess. Nobody knows who is correct. People only comment on the result. When a decision is proven to be wrong, then everyone will start saying that “you should do this or that because of this and that”! It’s human.
2) If you want to shun away from volatile equity market especially if you seriously believe that the bull is coming to an end, start switching to fixed income instrument. You may not need to do it instantly like disposing all your shares in a day. You can do it gradually by reducing your equity portfolio's size.
3) If you want to invest in fixed income instrument, avoid one with currency risk. And buy investment-grade local bonds (or bond funds).
4) If you buy SGS, you can either buy the existing ones or newly-issued bonds. Personally, I will advise you not to select bonds with very long maturity period such as ten years. Find one that is you are comfortable with the yield and maturity period, say three or five years. If you don’t want to go through this pain, then pay for a fund manager.
5) Assuming that your analysis is correct, you had protected your loots. You shall wait for the dust to settle. When that day comes, i.e. business cycle on recovery again, if your bonds expired, you will get back your capital. Otherwise you can sell it in the open market and get your capital gain. You have huge amount of cash and is ready for another upswing of the business cycle. And the story continues.
Conclusion
So here we come to an end on my sharing of long-term winning strategy in good times and in bad times. Lastly, in case you’ve forgotten the ultimate objective of all these efforts in investment, I need to remain you again. The ultimate objective is not to buy a bigger house or car. Buying bigger car is one “xxxxx” things to do. No offence to anyone but if you read books from successful investment gurus or wealth creation experts, you will know what I mean. Early gratification is unwise. The ultimate objective is for comfortable retirement or even early retirement (as in the case of Robert Kiyosaki) where you never worry about sufficient savings till the day you meet your Maker; where you can continue with the lifestyle you used to have with your wife. If we can survive through a few business cycles successfully, this will not be just a dream.
Sunday, November 4, 2007
Investment Strategy - Surviving The Economic Downturn (Part III)
Determination Of Bond Price
Before we continue, if you just want to buy bond, you can skip this session. You don’t really need to know how bond price is determined especially if you buy bond fund. The fund manager is paid to get some brain cells killed. But if you like to know more, then this session is important. Everyone knows how the price of a stock is determined – supply and demand. But for bond, it is not by supply and demand. It is purely mathematical. Firstly, for newly issued bonds, every unit will be priced at $1,000. Note that price of bonds are quote based on par value of $100. This is different from equity fund; just accept it. After a bond is issued, the price will change. To know how we determine existing bond’s price, let’s go through the elements that will affect bond price:
- Time (or maturity period)
- Coupon rate
- Future value (par value at redemption)
- Current interest rate or yield
I won’t go through the definition again. If you look at these elements carefully, you will realised that only the yield will change from time to time. The maturity period (or the remaining life), the coupon rate and future value cannot change. Therefore, only yield will change thus directly affecting the price. Or only the price can change and it will directly affect the yield. Their fate is intertwined. With a financial calculator (or using a web-based bond calculator), if you increase the yield, the price will fall and vice versa. This is the inverse relationship between bond price and yield (or current interest rate). Like I say, it is purely mathematical. Play around with the calculation and you will understand.
Inverse Relationship Between Market Interest Rate And Bond Price
You MUST remember this by hard even if you don’t understand - the inverse relationship between bond price and market interest rate. When interest rate goes up, bond price fall; when interest rate comes down, bonds price rise. So if the government (e.g. US’s Fred) increase their interest rate, the banks will follow and existing bond price will drop and vice versa. Again this is purely mathematical. No tricks and not by supply and demand. We can prove this easily with a financial calculator. But even without a calculator, we can also understand it with our common sense. Firstly, when the government announce an increase in interest rate, you wouldn’t buy existing bond, i.e. those that are already issued and available in the open market. Why? This is because the new bonds will be issued with comparatively higher coupon rates following the government’s new interest rate direction. Remember that I say the coupon rate of a bond is fixed? Thus you have no incentive to buy existing bonds with comparatively lower coupon rate. As such, these existing bond prices’ will fall and adjusted immediately such that the yield equals to current interest rate, generally speaking. Thereafter, you are indifferent to whether you should buy the newly issued bonds or existing bonds since they all gives you about the same yield. I repeat again – the YIELD should be your ultimate focus.
“Hey, I am an artist; I have no clue what you are talking about!”
Then forget about the above explanation and just remember the relationship by hard! We are going to use this knowledge to set our investment horizon; our strategy. Please take note that I am not talking about timing the market (buy in December and sell in January) but setting investment horizon. Let's say the economy just recovers from recession, interest rates are generally low. In the process of recovery to full-blown bull market, the government will increase the interest rate gradually. Imagine you bought a 10-year bond before economic recovery, say in 2003 and your initial intention was to hold it until maturity. Then you witnessed strong economic recovery and a few interest rate hikes. And everyone is making tonnes of money from equity. You gave up and decided to sell your bond before its maturity but you need to sell at a capital loss.
Let’s see how much you have learnt. My first one million dollar question:
Q. When is the best time to buy bond?
A. …….. Don’t know.
At the peak of a business cycle! The economy is bullish and interest rate is high. Everyone knows that what goes up must come down. It’s a matter of time. So if you believe that the bull run is over and recession may start in 2008, now is the best time to get out of equity and switch to bonds. When global economy really goes into recession for next few years, interest rate will fall. Governments will cut rates to boost business investment. And what happen when interest rate fall? Your bond price will goes up and you have two easy options:
1) Continue to hold and earn your higher coupon.
2) Sell it in the market for capital gain.
To formulate strategy, understanding this relationship is very important. If you don’t understand then remember by hard.
In The Event Of Default
I mentioned previously that the borrower must deliver its promise “without fail”. Although the borrower guarantees to pay you back on maturity date, it does not mean that Bonds are risk-free. What if the company fold up along the way? If you really want to play safe, you can lend to the government instead. Since the corporate bonds (or commonly known as debentures) carries a higher risk compare to the government bonds (on apple-to-apple basis), its coupon rate tends to be higher, all else remains constant. Let me illustrate this with an excerpt from an article “Corporate bonds risky on two counts” in Business Times during recent recession.
“SOME investors have been tempted into investment-grade corporate bonds this year because yields have been relatively attractive compared to money market returns. But events in the past few months have illustrated the risk of these investments. US and European bank and corporate bonds have been downgraded. Ford Motor's benchmark bond, which has been regarded as investment grade, is another example of the risks involved. Just over a week ago, Ford's ten-year bond maturing in 2011 was priced on a yield of 9.25 per cent. This was a spread of 565 basis points, or 5.65 percentage points, above 10-year US Treasury bonds, which were yielding 3.6 per cent. Such a spread is generally allocated to high-risk bonds. "
Business Times - 21 Oct 2002
Archived Hock Lock
Before we continue, if you just want to buy bond, you can skip this session. You don’t really need to know how bond price is determined especially if you buy bond fund. The fund manager is paid to get some brain cells killed. But if you like to know more, then this session is important. Everyone knows how the price of a stock is determined – supply and demand. But for bond, it is not by supply and demand. It is purely mathematical. Firstly, for newly issued bonds, every unit will be priced at $1,000. Note that price of bonds are quote based on par value of $100. This is different from equity fund; just accept it. After a bond is issued, the price will change. To know how we determine existing bond’s price, let’s go through the elements that will affect bond price:
- Time (or maturity period)
- Coupon rate
- Future value (par value at redemption)
- Current interest rate or yield
I won’t go through the definition again. If you look at these
 elements carefully, you will realised that only the yield will change from time to time. The maturity period (or the remaining life), the coupon rate and future value cannot change. Therefore, only yield will change thus directly affecting the price. Or only the price can change and it will directly affect the yield. Their fate is intertwined. With a financial calculator (or using a web-based bond calculator), if you increase the yield, the price will fall and vice versa. This is the inverse relationship between bond price and yield (or current interest rate). Like I say, it is purely mathematical. Play around with the calculation and you will understand.
Inverse Relationship Between Market Interest Rate And Bond Price
You MUST remember this by hard even if you don’t understand - the inverse relationship between bond price and market interest rate. When interest rate goes up, bond price fall; when interest rate comes down, bonds price rise. So if the government (e.g. US’s Fred) increase their interest rate, the banks will follow and existing bond price will drop and vice versa. Again this is purely mathematical. No tricks and not by supply and demand. We can prove this easily with a financial calculator. But even without a calculator, we can also understand it with our common sense. Firstly, when the government announce an increase in interest rate, you wouldn’t buy existing bond, i.e. those that are already issued and available in the open market. Why? This is because the new bonds will be issued with comparatively higher coupon rates following the government’s new interest rate direction. Remember that I say the coupon rate of a bond is fixed? Thus you have no incentive to buy existing bonds with comparatively lower coupon rate. As such, these existing bond prices’ will fall and adjusted immediately such that the yield equals to current interest rate, generally speaking. Thereafter, you are indifferent to whether you should buy the newly issued bonds or existing bonds since they all gives you about the same yield. I repeat again – the YIELD should be your ultimate focus.
“Hey, I am an artist; I have no clue what you are talking about!”
Then forget about the above explanation and just remember the relationship by hard! We are going to use this knowledge to set our investment horizon; our strategy. Please take note that I am not talking about timing the market (buy in December and sell in January) but setting investment horizon. Let's say the economy just recovers from recession, interest rates are generally low. In the process of recovery to full-blown bull market, the government will increase the interest rate gradually. Imagine you bought a 10-year bond before economic recovery, say in 2003 and your initial intention was to hold it until maturity. Then you witnessed strong economic recovery and a few interest rate hikes. And everyone is making tonnes of money from equity. You gave up and decided to sell your bond before its maturity but you need to sell at a capital loss.
Let’s see how much you have learnt. My first one million dollar question:
Q. When is the best time to buy bond?
A. …….. Don’t know.
At the peak of a business cycle! The economy is bullish and interest rate is high. Everyone knows that what goes up must come down. It’s a matter of time. So if you believe that the bull run is over and recession may start in 2008, now is the best time to get out of equity and switch to bonds. When global economy really goes into recession for next few years, interest rate will fall. Governments will cut rates to boost business investment. And what happen when interest rate fall? Your bond price will goes up and you have two easy options:
1) Continue to hold and earn your higher coupon.
2) Sell it in the market for capital gain.
To formulate strategy, understanding this relationship is very important. If you don’t understand then remember by hard.
In The Event Of Default
I mentioned previously that the borrower must deliver its promise “without fail”. Although the borrower guarantees to pay you back on maturity date, it does not mean that Bonds are risk-free. What if the company fold up along the way? If you really want to play safe, you can lend to the government instead. Since the corporate bonds (or commonly known as debentures) carries a higher risk compare to the government bonds (on apple-to-apple basis), its coupon rate tends to be higher, all else remains constant. Let me illustrate this with an excerpt from an article “Corporate bonds risky on two counts” in Business Times during recent recession.
“SOME investors have been tempted into investment-grade corporate bonds this year because yields have been relatively attractive compared to money market returns. But events in the past few months have illustrated the risk of these investments. US and European bank and corporate bonds have been downgraded. Ford Motor's benchmark bond, which has been regarded as investment grade, is another example of the risks involved. Just over a week ago, Ford's ten-year bond maturing in 2011 was priced on a yield of 9.25 per cent. This was a spread of 565 basis points, or 5.65 percentage points, above 10-year US Treasury bonds, which were yielding 3.6 per cent. Such a spread is generally allocated to high-risk bonds. "
Business Times - 21 Oct 2002
Archived Hock Lock
To be continue…..
Investment Strategy - Surviving The Economic Downturn (Part II)
Bond’s Credit Rating
Like movies in Singapore, bonds are also rated. There are high-risk bonds (like RA movie, risky for youth) and low risk bonds (like PG movie). As usual high-risk high gains and low risk low gain; you know the rule. The higher-risk bond naturally comes with higher coupon so as to compensate investors for assuming additional risk and vice versa. Currently, there are credit-rating agencies that businesses and investors frequently used. They are Standard & Poor's, Moody's and Fitch. Just to give you an idea on these agencies rating system:
1) Standard & Poor's
Investment Grade:
AAA : the best quality companies, reliable and stable
AA : quality companies, a bit higher risk than AAA
A : economic situation can affect finance
BBB : medium class companies, which are satisfactory at the moment
Non-Investment Grade (also known as junk bonds):
BB : more prone to changes in the economy
B : financial situation varies noticeably
CCC : currently vulnerable and dependent on favourable economic conditions to meet its commitments
CC : highly vulnerable, very speculative bonds
C : highly vulnerable, perhaps in bankruptcy or in arrears but still continuing to pay out on obligations
CI : past due on interest
R : under regulatory supervision due to its financial situation
SD : has selectively defaulted on some obligations
D : has defaulted on obligations and S&P believes that it will generally default on most or all obligations
NR : not rated
2) Moody's
Investment grade:
Aaa : highest quality, with minimal credit risk.
Aa1, Aa2, Aa3 : high quality and are subject to very low credit risk.
A1, A2, A3 : upper-medium grade and are subject to low credit risk.
Baa1, Baa2, Baa3 : subject to moderate credit risk. They are considered medium-grade and as such may possess certain speculative characteristics.
Speculative grade:
Ba1, Ba2, Ba3 : speculative elements and are subject to substantial credit risk.
B1, B2, B3 : speculative and are subject to high credit risk.
Caa1, Caa2, Caa3 : poor standing and are subject to very high credit risk.
Ca : highly speculative and are likely in, or very near, default, with some prospect of recovery of principal and interest.
C : lowest rated class of bonds and are typically in default, with little prospect for recovery of principal or interest.
3) Fitch
Investment Grade:
AAA : the best quality companies, reliable and stable
AA : quality companies, a bit higher risk than AAA
A : economic situation can affect finance
BBB : medium class companies, which are satisfactory at the moment
Non-Investment Grade (also known as junk bonds):
BB : more prone to changes in the economy
B : financial situation varies noticeably
CCC : currently vulnerable and dependent on favourable economic conditions to meet its commitments
CC : highly vulnerable, very speculative bonds
C : highly vulnerable, perhaps in bankruptcy or in arrears but still continuing to pay out on obligations
D : has defaulted on obligations and Fitch believes that it will generally default on most or all obligations
NR : not publicly rated
Obviously, triple A bonds are the most reliable. Bonds issued by Singapore Government are rated “AAA”. Do I memorise all these agencies rating system? Of course not! Not even for my examination…. crazy. But my lecture taught me a short-cut method to differentiate between investment grade bond and junk bond. If you are risk averse, then avoid any bond where you can’t find even one cap-locked “A” on the rating. In this case, you are sure to avoid junk bond. A junk bond is also known as a "high-yield bond" or "speculative bond". These bonds have higher credit risk are usually purchased for speculative purposes. Junk bonds typically offer interest rates three to four percentage points higher than safer government issues.
How to Invest In Bonds
You can invest in bond by placing your money with a fund manager and let him invest for you…. at a small commission of course. In this case, you are buying a bond fund, or commonly known as fixed income fund. As a bond fund does not require active trading, the expense ratio is generally low as compared to equity funds. With the pool of money, the fund manager will invest in many bonds. The advantages:
1) If you have no time for this, let the fund manager do it for you.
2) You lack the expertise so let the experts to do it for you.
3) Bond fund allows you to diversify your risk, i.e. risk is spread across.
4) If you intend to invest for a very long time especially if you’re at retirement age, it’s better that the fund manager do it for you. In this case, you don’t have to keep buying bonds when existing one expires. Also you won’t have a problem with the re-investment assumption of the bond yield. This is a bit technical; you can skip it.
Alternatively, you can buy bond directly from a company or the government. In Singapore context, our government-issued bond is known as the Singapore Government Securities (SGS). If you buy a bond directly, your investment will come to an end at the maturity date stated on the paper. If you invest through a fund manager, all else remains constant, it will be there for as long as possible. Note that for all my subsequent sharing and illustrations, I will assume that you buy the bond directly instead of buying a bond fund.
You can invest in any kinds of bonds through Fundsupermart.com. There are other distributors such as banks but since I am more familiar with Fundsupermart.com, I’ll use them for illustration purposes (“free marketing”). I had an investment account with Fundsupermart.com but I don’t have any financial interest in that fund distribution company. Assuming that you want to buy SGS, from Fundsupermart.com, you will find the following list of SGS:
Like movies in Singapore, bonds are also rated. There are high-risk bonds (like RA movie, risky for youth) and low risk bonds (like PG movie). As usual high-risk high gains and low risk low gain; you know the rule. The higher-risk bond naturally comes with higher coupon so as to compensate investors for assuming additional risk and vice versa. Currently, there are credit-rating agencies that businesses and investors frequently used. They are Standard & Poor's, Moody's and Fitch. Just to give you an idea on these agencies rating system:
1) Standard & Poor's
Investment Grade:
AAA : the best quality companies, reliable and stable
AA : quality companies, a bit higher risk than AAA
A : economic situation can affect finance
BBB : medium class companies, which are satisfactory at the moment
Non-Investment Grade (also known as junk bonds):
BB : more prone to changes in the economy
B : financial situation varies noticeably
CCC : currently vulnerable and dependent on favourable economic conditions to meet its commitments
CC : highly vulnerable, very speculative bonds
C : highly vulnerable, perhaps in bankruptcy or in arrears but still continuing to pay out on obligations
CI : past due on interest
R : under regulatory supervision due to its financial situation
SD : has selectively defaulted on some obligations
D : has defaulted on obligations and S&P believes that it will generally default on most or all obligations
NR : not rated
2) Moody's
Investment grade:
Aaa : highest quality, with minimal credit risk.
Aa1, Aa2, Aa3 : high quality and are subject to very low credit risk.
A1, A2, A3 : upper-medium grade and are subject to low credit risk.
Baa1, Baa2, Baa3 : subject to moderate credit risk. They are considered medium-grade and as such may possess certain speculative characteristics.
Speculative grade:
Ba1, Ba2, Ba3 : speculative elements and are subject to substantial credit risk.
B1, B2, B3 : speculative and are subject to high credit risk.
Caa1, Caa2, Caa3 : poor standing and are subject to very high credit risk.
Ca : highly speculative and are likely in, or very near, default, with some prospect of recovery of principal and interest.
C : lowest rated class of bonds and are typically in default, with little prospect for recovery of principal or interest.
3) Fitch
Investment Grade:
AAA : the best quality companies, reliable and stable
AA : quality companies, a bit higher risk than AAA
A : economic situation can affect finance
BBB : medium class companies, which are satisfactory at the moment
Non-Investment Grade (also known as junk bonds):
BB : more prone to changes in the economy
B : financial situation varies noticeably
CCC : currently vulnerable and dependent on favourable economic conditions to meet its commitments
CC : highly vulnerable, very speculative bonds
C : highly vulnerable, perhaps in bankruptcy or in arrears but still continuing to pay out on obligations
D : has defaulted on obligations and Fitch believes that it will generally default on most or all obligations
NR : not publicly rated
Obviously, triple A bonds are the most reliable. Bonds issued by
 Singapore Government are rated “AAA”. Do I memorise all these agencies rating system? Of course not! Not even for my examination…. crazy. But my lecture taught me a short-cut method to differentiate between investment grade bond and junk bond. If you are risk averse, then avoid any bond where you can’t find even one cap-locked “A” on the rating. In this case, you are sure to avoid junk bond. A junk bond is also known as a "high-yield bond" or "speculative bond". These bonds have higher credit risk are usually purchased for speculative purposes. Junk bonds typically offer interest rates three to four percentage points higher than safer government issues.
How to Invest In Bonds
You can invest in bond by placing your money with a fund manager and let him invest for you…. at a small commission of course. In this case, you are buying a bond fund, or commonly known as fixed income fund. As a bond fund does not require active trading, the expense ratio is generally low as compared to equity funds. With the pool of money, the fund manager will invest in many bonds. The advantages:
1) If you have no time for this, let the fund manager do it for you.
2) You lack the expertise so let the experts to do it for you.
3) Bond fund allows you to diversify your risk, i.e. risk is spread across.
4) If you intend to invest for a very long time especially if you’re at retirement age, it’s better that the fund manager do it for you. In this case, you don’t have to keep buying bonds when existing one expires. Also you won’t have a problem with the re-investment assumption of the bond yield. This is a bit technical; you can skip it.
Alternatively, you can buy bond directly from a company or the government. In Singapore context, our government-issued bond is known as the Singapore Government Securities (SGS). If you buy a bond directly, your investment will come to an end at the maturity date stated on the paper. If you invest through a fund manager, all else remains constant, it will be there for as long as possible. Note that for all my subsequent sharing and illustrations, I will assume that you buy the bond directly instead of buying a bond fund.
You can invest in any kinds of bonds through Fundsupermart.com. There are other distributors such as banks but since I am more familiar with Fundsupermart.com, I’ll use them for illustration purposes (“free marketing”). I had an investment account with Fundsupermart.com but I don’t have any financial interest in that fund distribution company. Assuming that you want to buy SGS, from Fundsupermart.com, you will find the following list of SGS:

Firstly, please focus on the yield. The yield takes into account current selling price and the coupon. Pick one which you are comfortable. Of course if you pick the highest yield (3.12%), that bond has another 19.34 years before it matures. This is because the longer the maturity period, the higher the yield and vice versa. So assuming that you want a bond with around five years maturity and click on “NX03100Z”, the following details will appear.

Now stay focus. The fact sheet will show the bond’s remaining life; it’s annual coupon and yield. The coupon rate is the interest that you will actually receive calculated based on 2.25% x par value (in multiples of $1,000 per unit). Par value; not market value (bond price can move up and down). So for every unit you bought, you will receive $22.5 every year. The yield tells you your actual rate of returns because yield takes into account your purchase price. In this case, the current indicative price is $98.5. So every unit will cost you $985 - that is below the par value of $1,000! And you know that you will receive $1,000 back at maturity. That is why your actual rate of returns (the yield) is higher than the coupon rate. Make sense?
“Hey I am a doctor and I still don’t understand what you are talking about!”
In that case, just look at the yield and maturity period. Pick one bond that you are comfortable with the yield and maturity. Still cannot? Get yourself a fund manager..
To be continue…….
Saturday, November 3, 2007
Investment Strategy - Surviving The Economic Downturn (Part I)
Riding The Business Cycle
For the smart ones, they know that the equity market is too hot. It is like setting historical record everyday and large daily fluctuation has been accepted. Coupled with rising oil price to near historical high in today’s dollar value plus US housing slump, only idiots will ignore the likely consequence. Now I have more friends asking me about bonds. To those who studied accounting or finance, or people working in finance (or related) sector, it is nothing complex. But to many retail investors, it may not sound easy. And I had been talking about using bonds to protect our earning in times of economic downturn, i.e. the down swing of the business cycle. This is the time when we need to exit from equity and to place our earnings into other defensive assets that have negative correlation with the economy yet yielding reasonable returns at the same time. Otherwise, you will see your stocks and equity fund plunging thus returning all your years of earnings back to Ms Market. Remember, protecting your earning is more important than anything else. 不要白忙一场。
“But I thought as a follower of Warren Buffett, our investment horizon should be like indefinite?”
Unfortunately as a retail investor, we are unable to do exactly what Warren Buffett has been doing. We don’t even have a hundred thousand cash in bank. There are so many things Warren Buffett can do that we can’t. For example, we can’t buy over a company and not even a significant stake. We shall use Warren Buffett’s strategy but intelligently. Understand our limitation and be flexible in formulating our strategy is the key to success.
So to protect our earnings, if we are expecting a downturn, we need to switch our money from equity to fixed income instruments. These are assets that provides steady annual returns and, generally, with capital protection. I will explain why I used the word “generally” later. A bond is a fixed income security.
What Is A Bond?
Bonds are basically loans, and you are the lender. Companies or government need to borrow money to fund their projects and you lend it to them. These borrowers promise to return back your money in full at maturity date. This means that if the “contract” says that ABC Pte Ltd borrows $10,000 from you for 5 years, at the end of the fifth year, $10,000 will be returned back to you. Along the way, the bond price may fluctuate but that is none of their problem. In addition, the borrower will also promise to pay the bondholders a fee yearly or half yearly without fail. You may call this fee as interest but the official term is “coupon”. Nothing comes for free in this world. Note that we take this word “without fail” very seriously because if a borrower fails to deliver its promise, it has defaulted and there is a serious repercussion. I’ll come back to this point later. The following are some of the terminologies that you should know:
1) Maturity period. This is the period of the loan stated on the paper. But if you purchase the bond from the open market, then you need to know the remaining life from the date of your purchase to its expiry date.
2) Coupon rate. This is a FIXED rate (you can call it interest rate) stated on the paper. Rain or shine, the borrower must honour it otherwise it has defaulted.
3) Yield. Yield is the actual returns of investing in a bond. I repeat, your actual returns is the yield, not the coupon rate. This should be your main focus if you are investing in bonds.
Who Are The Issuers?
Generally, bonds are issue by the government (e.g. local municipal, government agencies) or companies. Take note that for corporate bonds, we usually call it “debentures”. But for simplicity sake, throughout my articles, I’ll just use the word bond. Let’s say that both the government and a company issue a bond with same maturity period, is the coupon rate going to be the same? If not, which one should have a higher or lower rate? Given a choice, where would you park your money? Well, you don’t need an MBA in finance to answer this question. If comparing on apple-to-apple basis, obviously money lend to the government is the safest. Your decision may only change if the company offers a much higher coupon rates for a similar bond. So you now know that if the government and a company issues bond with the same characteristics, then the corporate bonds must come with higher coupon rate otherwise nobody is going to take it up.
“So you mean buying government bond has zero risk?”
Well, generally it should be but sometimes “xxx” happens. In August 1998, a financial crisis hit Russia (also called "Rouble crisis") just a year after Asian Financial Crisis. While Asian Financial Crisis circled around huge currency devaluation, Russian’s Financial Crisis was ignited by commodity prices. The decline in world commodity prices then hit countries that depend heavily on the export of raw materials, such as oil. As petroleum, natural gas, metals, and timber accounted for more than 80% of Russian exports, the country was vulnerable to swings in world prices. The sharp decline in the oil price and non-payment of taxes by the energy and manufacturing industries had severe consequences for Russia. This caused the Russian Government to default on their bonds. One of the victims was Long-Term Capital Management which I mentioned in my previous article on hedge funds.
But generally, and especially in Singapore context, it is very safe to lend your money to the government. I am willing to put my head on it. Seriously, do you really think that Singapore Government need to borrow from you to finance their project? Singapore is one (and may be the only one) of the countries that have zero national debts. Many years ago, my lecturer used to tell us “our government never borrow, they only lend”. Referring to the MAS website, it will tell you that Singapore Government issues bond not because they need it, but to develop and nurture the bond market in Singapore. (Shouldn’t they nominate me for National Day Award?)
“Is there other easier and more objective method for me to assess the risk of a bond?”
Yes there is – by looking at the credit-rating of a bond.
To be continue……
For the smart ones, they know that the equity market is too
 hot. It is like setting historical record everyday and large daily fluctuation has been accepted. Coupled with rising oil price to near historical high in today’s dollar value plus US housing slump, only idiots will ignore the likely consequence. Now I have more friends asking me about bonds. To those who studied accounting or finance, or people working in finance (or related) sector, it is nothing complex. But to many retail investors, it may not sound easy. And I had been talking about using bonds to protect our earning in times of economic downturn, i.e. the down swing of the business cycle. This is the time when we need to exit from equity and to place our earnings into other defensive assets that have negative correlation with the economy yet yielding reasonable returns at the same time. Otherwise, you will see your stocks and equity fund plunging thus returning all your years of earnings back to Ms Market. Remember, protecting your earning is more important than anything else. 不要白忙一场。
“But I thought as a follower of Warren Buffett, our investment horizon should be like indefinite?”
Unfortunately as a retail investor, we are unable to do exactly what Warren Buffett has been doing. We don’t even have a hundred thousand cash in bank. There are so many things Warren Buffett can do that we can’t. For example, we can’t buy over a company and not even a significant stake. We shall use Warren Buffett’s strategy but intelligently. Understand our limitation and be flexible in formulating our strategy is the key to success.
So to protect our earnings, if we are expecting a downturn, we need to switch our money from equity to fixed income instruments. These are assets that provides steady annual returns and, generally, with capital protection. I will explain why I used the word “generally” later. A bond is a fixed income security.
What Is A Bond?
Bonds are basically loans, and you are the lender. Companies
 or government need to borrow money to fund their projects and you lend it to them. These borrowers promise to return back your money in full at maturity date. This means that if the “contract” says that ABC Pte Ltd borrows $10,000 from you for 5 years, at the end of the fifth year, $10,000 will be returned back to you. Along the way, the bond price may fluctuate but that is none of their problem. In addition, the borrower will also promise to pay the bondholders a fee yearly or half yearly without fail. You may call this fee as interest but the official term is “coupon”. Nothing comes for free in this world. Note that we take this word “without fail” very seriously because if a borrower fails to deliver its promise, it has defaulted and there is a serious repercussion. I’ll come back to this point later. The following are some of the terminologies that you should know:
1) Maturity period. This is the period of the loan stated on the paper. But if you purchase the bond from the open market, then you need to know the remaining life from the date of your purchase to its expiry date.
2) Coupon rate. This is a FIXED rate (you can call it interest rate) stated on the paper. Rain or shine, the borrower must honour it otherwise it has defaulted.
3) Yield. Yield is the actual returns of investing in a bond. I repeat, your actual returns is the yield, not the coupon rate. This should be your main focus if you are investing in bonds.
Who Are The Issuers?
Generally, bonds are issue by the government (e.g. local municipal, government agencies) or companies. Take note that for corporate bonds, we usually call it “debentures”. But for simplicity sake, throughout my articles, I’ll just use the word bond. Let’s say that both the government and a company issue a bond with same maturity period, is the coupon rate going to be the same? If not, which one should have a higher or lower rate? Given a choice, where would you park your money? Well, you don’t need an MBA in finance to answer this question. If comparing on apple-to-apple basis, obviously money lend to the government is the safest. Your decision may only change if the company offers a much higher coupon rates for a similar bond. So you now know that if the government and a company issues bond with the same characteristics, then the corporate bonds must come with higher coupon rate otherwise nobody is going to take it up.
“So you mean buying government bond has zero risk?”
Well, generally it should be but sometimes “xxx” happens. In August 1998, a financial crisis hit Russia (also called "Rouble crisis") just a year after Asian Financial Crisis. While Asian Financial Crisis circled around huge currency devaluation, Russian’s Financial Crisis was ignited by commodity prices. The decline in world commodity prices then hit countries that depend heavily on the export of raw materials, such as oil. As petroleum, natural gas, metals, and timber accounted for more than 80% of Russian exports, the country was vulnerable to swings in world prices. The sharp decline in the oil price and non-payment of taxes by the energy and manufacturing industries had severe consequences for Russia. This caused the Russian Government to default on their bonds. One of the victims was Long-Term Capital Management which I mentioned in my previous article on hedge funds.
But generally, and especially in Singapore context, it is very safe to lend your money to the government. I am willing to put my head on it. Seriously, do you really think that Singapore Government need to borrow from you to finance their project? Singapore is one (and may be the only one) of the countries that have zero national debts. Many years ago, my lecturer used to tell us “our government never borrow, they only lend”. Referring to the MAS website, it will tell you that Singapore Government issues bond not because they need it, but to develop and nurture the bond market in Singapore. (Shouldn’t they nominate me for National Day Award?)
“Is there other easier and more objective method for me to assess the risk of a bond?”
Yes there is – by looking at the credit-rating of a bond.
To be continue……
Wednesday, September 12, 2007
Guaranteed Strategy - Invest In Brand Power (Part II)
Brand Power: Popular Bookstore
How to know whether Popular has a strong brand? Only an idiot will ask such a question because almost every Singaporean heard of Popular and visited its bookstore at least once in his/her lifetime. If you take a walk to Popular at the end of the year, you will be impressed. This because many parents will spend on books and stationeries for their children before school re-opened. I did that too, for my student. Almost 10 tens ago, I was a Sunday School teacher then. Besides bible and prayers in class, I love to play simple games with my little students. I invented many games and I spend on little gifts out of my own pocket. So I went to Popular, grabbed a basket and swept the packed stationery into my basket. People were looking at me and since I was relatively young then (and still young now!), most probably I would be perceived to be a teacher. The important question here is: why didn't I spent in a small bookstore located around the neighbourhood? How to explain the fact that I "automatically walked into Popular" to purchase my gift?
Valuations
I had gone through Popular’s financial reports for past few years. My spreadsheet auto-compute the ratios and my interpretation as follow:


- Profit & loss. Since 2004, Popular’s turnover has been on a steady up trend. For the financial year ended Apr 2007, turnover has a compounded annual growth rate of 4.65%. However, administrative expenses have also increased steadily over the year mainly due to labour cost and rental expense. Every Popular’s outlet requires large floor area and thus resulting in high rental expense. Popular’s finance expense has been very low. It has a very low gearing of less than 10% due to low borrowings. The net profit has fluctuated badly for last 3 years like a roller coaster and this is not something that will attract value investors.
- Liquidity. Popular’s liquidity is acceptable at around 1.8:1. Popular has about 47 cents cash to meet every $1 debt obligations.
- An important strength of popular is that it is cash rich. For every share you invest in, it is supported by 11 cents. Assuming at current price of 30 cents, you actually pay 19 cents for its assets.
- Margin. The operating margin is thin and has been fluctuating since 2004. This is a big negative as we would like to invest in a company with a more stable profit and growth.
- Due to the fluctuation in net profit, Popular’s return on equity suffers the same fate.
- PE. Assuming at price of 30 cents in Aug 2007, Popular is priced at 12 times PE. With current bullish market, 12 times PE is considered to be attractive.
- NTA. With continuous growth since 2004, Popular’s net assets also grew from around 27 cents to 30 cents in Aug 2007. As such, the PTB ratio is about 1 time. This may not look attractive but is reasonable.
- Business growth. Popular’s retail and distribution business has been growing steadily at about 5% per year. However, the publishing and e-learning business seems to be running out of steam. Data also suggest that Popular enjoy higher growth in Malaysia followed by Singapore. In 2007, Popular announced the development of two residential properties; one at Shelford road and another one at Robin road. With strong demand for properties in Singapore, I believed that cash used in property development would enhance shareholders’ value very soon. On 10 Sep 2007, Popular issued their first quarter result for financial period ended 2008. On month-on-month basis, Popular’s profit after tax increased by nearly 40%. Higher chance is that Popular net profit for 2008 is likely to exceed that of 2007.
So, it is clear that Popular enjoys customer loyalty and thus recurrence sales. It is relatively cash rich and started to invest in lucrative property market. While it is difficult to quantify whether current price of 30 cents is undervalue, in my opinion, it is certainly not overvalued. Its share price has been rather stagnant for quite sometime. The reason was partly due to disappointed 2007 result plus US subprime crisis that affect global market. While it may be difficult to determine if Popular’s business will grow steadily, it has an important catalyst, the two residential properties. I believe that 30 cents is a good buy for Popular and has invested in it since early 2007.
Lastly, in the first part of this article, I specially highlighted the term “gut feeling”. This is an important element when comes to investment. When I discussed with friends on whether if “Warren Buffett’s can be duplicated”, we came concluded that Warren Buffett cannot be duplicated. We may learn his investment methodology, follow his teaching and put it into practice. But there is just one thing that cannot be taught – gut feeling. We believed that with superior knowledge and strategy, supported with advance information system and special privilege to reach the top management of a company still doesn’t guarantee a 100% correct investment decision. There is just one more element that is needed, i.e. gut feeling. Take Popular for example, looking at its performance so far, another analyst may find the company's business has nothing to shout about, but I felt differently. This is my gut feeling.
Tuesday, September 11, 2007
Guaranteed Strategy - Invest In Brand Power (Part I)
The title may look daring and arrogant, but it is backed by years of experience. If you are a novice in stock investment, today is your lucky day. Today I’ll share with you on a long-term winning strategy of stock investment backed by the experience of a renowned investment gurus: Warren Buffett. In some of my earlier articles, I had discussed on wonderful companies such as Breadtalk and Super Coffeemix. I had also produced Warren Buffett’s top 10 holdings as at Aug 2007. Actually, these articles had indirectly pointed out this long-term winning strategy.
There are many approaches/theory exist today on stock investment strategy. But the simplest method tends to work in all situations. This method that I am talking about is to invest in a company with strong brand name. This is an extremely easy investment strategy that will always work in any stock market; in any country and for any kind of investor as long as you believe in value investing. I learned it from Warren Buffett, I tried it and now I share it. With this approach, you are only required to do two things:
1) Identify household/consumer products/services with strong brand especially those that meet people’s basic needs.
2) Determine if the company that offers these products/services is undervalued and with growth potential.
Let me elaborate these two points. Warren Buffett’s top holdings are mainly products/services that people used frequently, if not daily. For example shavers, toothpaste, soft drinks, coffee etc. A product/service that has a strong brand will lead to consumers’ loyalty and as a result, enjoy recurrence sales. You can see it in the supermarket, or even right at home. You will be surprised to know that sometimes people buy a product without actually making a choice. This may be due to “follow the crowd” behaviour, or subconsciously they just pick up the product because they heard the brand too often. I am sure that to identify this kind of products/services is a simple task even for a primary school boy. There is still another way to test which product or service has strong brand name or I call it “brand power”. You do a test among your friends randomly by giving them an article and they are suppose to say whatever comes out of their mind within split second. Yes, that is a test of their sub-consciousness. For example, you can give them:
- Fast food
- Soft drink
- Car
- Computer
- Sports shoe
- Insurance company
- School
You collect these data and you will know the popularity of each of them. Anyway, I don’t expect you to do this unless you really have nothing better to do.
After you have identified such a product, assuming that the company selling the product is listed, your next job is to determine whether the company is undervalued and with growth potential. This requires analytical skills and gut feeling. Yes, I say gut feeling. If you read analysts’ report regularly, you will know that everyone of them has a secret formula to derive a company’s value so as to recommend a “buy”, “sell” or “hold” etc. One thing for sure, you won’t know how they come up with these “magic” figures, and therefore, their recommendation. Let say even if you know, as a retailer, I don’t think we want to do this. I mean you don’t expect me to do a “discounting cashflow”, “free cashflow”, “return on investment”? I will only if someone pays me high salary to do it. Besides, different analysts with the same formula with come out with different answers, I guarantee. And then the next question is, who is correct? I say forget it. In my opinion, for a retail investor, an idiot-proof method is simply to compare a company’s share price with:
- Share prices of a competitor selling about the same product/service
- Compare the PE with the industry/competitor
- Compare with the company’s asset backings especially CASH!!!
- Determine the company's market share.
- Identify book orders
- Identify corporate actions to expand and whether shares price takes into account such announcements.
That’s what I do for company such as Breadtalk, Super Coffeemix, Aqua Terra, Want Want, Metro etc. With the exception of Aqua Terra which I recommended to a few friends only recently, the rest of the companies had increased the wealth of my friends/colleagues.
If you go through the above exercise thoroughly, you will be able to say something like this, “I think this company’s share price does not reflect its actual strength or progresses”. The word “I think” implies that the power of “gut feeling” has been deployed. Since this is the second time I mention on “gut feeling”, I’ll explain in detail later on. Once you got an answer, the next thing is to determine whether this particular company is growing. The good news is that the exercise you have just completed will more or less give you an answer on growth. You don’t believe? Ok, I’ll briefly repeat my story on Breadtalk again.
When I reviewed Breadtalk’s business again in Dec 2006, I discovered that they have been aggressive in expanding their business. From increasing their franchise outlets, they also bought over “Megabite” in China to compete the food court business there. Breadtalk also brought into Singapore the famous Tin Tai Feng (from Taiwan) and started to slice the cake of local food court business. With so many actions that, in my opinion, will soon be translated into revenue growth, Breadtalk’s share price hardly moves and was rather illiquid. Even if I cannot conclude that Breadtalk is undervalue at $0.23 then, but I can safely say that its price failed to factor in Breadtalk’s progresses. Even if I may still be wrong, gentleman, I won’t be that wrong; we are in a recovery market (and subsequently turns out to be a bull run). And do not forget that another food court operator “Food Junction” was priced above $0.60.
So lots of things are really commonsense. And I shall repeat my lecturer’s quote “commonsense is the least common human attribute”. There is another company with strong brand (household brand) that in my opinion, Mr Market had overlooked. I had recommended a “buy” on this company to some of my friends and colleagues and very soon, we will know if I am correct. I’ll demonstrate how I go through the two tasks: identify a company with strong brand; determine its value and growth potential.
This company is a popular bookstore: Popular Holdings.
To be continue……
Saturday, September 8, 2007
Warren Buffett's Top Ten
Isn’t it interesting to know Warren Buffett’s top 10 holdings? Hopefully there are some things for us to learn by looking at Warren Buffett’s favourite stocks. I have found an article from fool.com on Warren Buffett’s favourite stocks (dated 22 Aug 2007).
1) Coca-Cola - soft drinks
2) Wells Fargo - banking, insurance, investments, mortgage and consumer finance
3) American Express - credit cards, financial services, travel services
4) Procter & Gamble - consumer products such as Pampers, Tide, Ariel, Gillette, Pantene, Bounty, Folgers, Pringles
5) Johnson & Johnson - consumer products, medical devices and diagnostics and pharmaceutical
6) Burlington Northern Santa Fe - railway delivering cars, coal, clothing, games and nearly anything else found in homes and businesses
7) Wesco Financial - insurance, furniture rental, and steel service
8) Moody's - credit ratings, research and risk analysis
9) Anheuser-Busch - Bud Light and Budweiser (beer)
10) ConocoPhillips - petroleum exploration and production, refining, marketing and supply; natural gas gathering, processing and marketing.
Most of the top 10 companies are household names with very strong brand names globally and enjoy recurrence sales. The business of these companies is simple, with growth potential and easy to understand. Most of these companies offer products/services that meet consumers’ basic needs and has certain degree of immunity to the business cycle. For example, you always need a credit card, your decision to drink coke is not affected by economic crisis and you will still shave even in times of recession.
A few years ago, my coursemate and I were looking into Super Coffeemix, a listed company on the SGX. We believe that Super Coffeemix has most of the characteristics of a company that Warren Buffett will buy. The most obvious attribute is that it had huge market share for instant coffee in Singapore. However, it was also around that time that local tycoon Mr. Oei Hong Leong invested in the company at less than 30 cents. I was slow in action and subsequently refused to invest in Super Coffeemix. I was very obstinate as I hate buying shares at a price that is higher than those tycoons. I felt that if I do it, it is as good as giving money away to these rich men.
As expected, Super Coffeemix continued to report higher profit year after year and together with strong market sentiment, it share price surged 100% by Mar 2006. Then one of my friends, who was learning value investment asked for my opinion on Super Coffeemix. I replied that it is a wonderful company and shared with him on Super Coffeemix’s history. I recommended a “buy” even when the price had surged 100%. He bought it and lock in his profit when Super Coffeemix’s share price surged pass 60 cents. I told him that he had made a wrong move for failing to understand its growth potential; he failed to recognise Super Coffeemix’s brand-power. And what’s my problem? I am super obstinate.
In Jul 2007, just before the exposure of US subprime woes that cause global market to plunge, Mr Oei Hong Leong disposed off his entire 13.17% stakes in Super Coffeemix and bagged approx. $40 million profit!!! Supercoffee was trading at around $1 then.
In my next article, I will share and analyse another local company with strong brand.
Sunday, September 2, 2007
How To Evaluate A Company's Business (Part II)
In Dec 2006, I was flipping an investment journal searching for investment opportunity and I saw information on Breadtalk. Merely by glancing through some figure, I felt that something has changed and I decided to re-study Breadtalk’s business again. I downloaded Breadtalk’s annual reports and punched those figures into my calculator. I highlighted all the growth factors and focus especially on it’s franchise business. Without putting it together into a nice report, I concluded that Breadtalk’s fundamental has changed!!!
In 2004, I have a few reasons why we should avoid Breadtalk. But now, I have even more reasons to invest in this company. I shared with a few colleagues and friends including Mr. Philip Comd (the one who says “by the time their franchise business become successful, the share price would have gone up”) to buy Breadtalk. Its share was quite illiquid then trading around $0.23 a share. But it doesn’t matter to me. Why? Because I am not trading, I am investing! That’s why! And after Breadtalk released its annual report for 2006 in Feb 2007, it just confirmed that my analysis is correct.
I like all my readers to remember this. Sometime Mr. Market overlooked a growth company. Here we have one good example. I am not suggesting that Breadtalk will definitely grow for the next five years, but its growth for the last few years has been impressive. Most importantly, Breadtalk now has attributes that Warren Buffett always look out for – growth, intrinsic value, strong brand, necessity, business that is simple to understand etc. Enough of talking, let’s go into Breadtalk’s financial statements.
I have a spreadsheet with formulated cells for ratio analysis. By punching in figures from a company’s annual reports, ratio computation will be done automatically. I also have my own rating system but it is classified. The followings are my interpretation of Breadtalk’s financial performance:

- Its liquidity is acceptable although it is below the ratio of 2:1. We need to understand that Breadtalk’s business is mostly in cash term and with low inventory. One thing for sure, they can’t and they won’t keep their bread overnight.
- NP margin has improved steadily, though still not impressive enough. If you asked me “how would I be impressed”, personally I would love 15% - 20% sustainable NP margin. Previously it has high GP margin but extremely thin NP margin. This goes to explain that it has high operational expenses such as labour and rental. However, I am sure that the management is aware of these problems and has controlled its bakery outlet expansion locally. Instead, they expanded their bakery outlet outside Singapore, particularly in China.
- Returns on equity (ROE) shows marked improvement indicates that company has deployed resources effectively thus generating shareholder value.
- Though gearing has increased, but by my personal yardstick, Breadtalk’s gearing is still healthy.
- PE was about 12 times in Dec 2006 and considered attractive then. It is about 22 times in Aug 2007.
- Price-to-book (PTB) ratio is definitely above 1 considers that Breadtalk does not need to invest heavily in assets. That’s why it has low NTA. Perfectly sensible to me. But in Aug 2007, the PTB is rather high due to higher share price.
- Dividend sucks. But for a growth company, it is perfectly ok not to distribute dividends. By the way, Warren Buffett doesn’t believe in giving out dividends. This is because he knows that if he gives out dividends, shareholders might put it in other lousy investments. In the hands of Warren Buffett, it will be compounded at around 25% a year.
- Breadtalk’s share issue is quite thin. Based on my experience, average small/mid cap companies tend to have around 500 million issued shares. For the year ended 31 Dec 2006, Breadtalk’s issued share is only approximately 200 million. You know what that means? That means when Mr. Market finds out what I discovered, Breadtalk’s share price will surge (and it did in mid-2007).
- The revenue growth from Bakery and food court are impressive. Its franchise business increased tremendously but we are still  waiting for it to translate into wonderful revenue contribution.
Breadtalk’s fundamental has changed. Besides franchise business, I am also excited on its food court business. In Jul 2007, I saw Breadtalk’s new food court “大食代” (Food Republic) below Suntec Conventional Hall. That food court, oh my god, it is fantastic. It is not just a food court, it’s a classy food court. It’s like back to old times, or as if you are dining in a library. Go visit that outlet but don’t go during weekends or peak hours.
3) Consensus reports
Have you forgotten that I am still touching on how to evaluate a business? This is part 2 of a previous article. Don’t get too carried away with Breadtalk. In fact, I am not suppose to cover financial analysis here. It is suppose to be just qualitative analysis. Anyway, what the hack! Now, there are tonnes of analysts writing their reports everyday but only handful are really, really good. The rest of them…. I better don’t comment else I might get beaten up. If you have friends working in broking/fund houses, go ask them how analysts rush their reports. They are trained no doubt, but take these analysts’ reports with a pinch of salt. In any case, their forecast figures for the next 3 years will change frequently after a company releases its financial report.
So now you realised that I didn’t forecast Breadtalk’s financial statement for next three years. I don’t forecast profit or losses; only God can see the future. I hope you are not disappointed. Notwithstanding all that I said above, there are also good analysts such as Ms Teh Hooi Ling, BT Senior Correspondent which I had introduced to many of my friends. Professional analysts have sources, huge database and connections to get latest information. They are also able to interview top management of a listed company easily. So by collating and studying the analysts’ reports, I can see if it concurs with my findings. If the answer is yes, then it is even highly probable that my analysis is correct. You want living example? Here’s one but you might think that it’s all bullshit. Nonetheless, I’ll still share with you. About two years ago, I was very interested in Ausgroup. I believed that it is a growth company which has been largely overlooked. Its share was rather illiquid until Ms the Hooi Ling issue a report in Business Times. Most of us bought it at around $0.25 - $0.30. Supported with growing profit, its share price skyrocketed to $2 in mid-2007. But we have already locked in our profit.
This article is a bit long; I have to end it here. In conclusion, open your eyes and ears especially when you are in a group or in shopping mall, and take note of things happening around you can help you to make correct investment decision. In this way, it mitigates our shortcomings as a retail investor.
Friday, August 31, 2007
Investment Based On The Character Of Those At The Helm
Dear readers, I found it! I done a search on Fundsupermart.com website and I found that article of a success story that I shared in my write-up “How to evaluate a company’s business (part I)” dated 30 Aug 2007. The following is an extract from the article, credit goes to Fundsupermart.com. Before we go on with the wonderful story, I like to declare that I have an investment account with Fundsupermart.com. But I do not have any business relationship with Fundsupermart.com.
-------------------------
December 26, 2002
This Cabbie's Worth A Million Bucks
G.K. Singam came to Singapore over 30 years ago with just $7 in his pocket. Today, he has an investment portfolio worth $1.1 million. He tells Fundsupermart Magazine where he has put his money to work and what he plans to invest in.
by Bharathi Rajan
Fundsupermart
Jan/Feb 2003 issue
Sim Wong Hoo Was His Regular Customer
In his 20 years as a taxi driver, "Singam" (as he's kn own to his colleagues) has driven possibly thousands of passengers. So over the years he has accumulated a wealth of knowledge from the conversations he has had with his customers who come from all walks of life. One of his most memorable encounters was with Creative Technology's Chairman Sim Wong Hoo. "Creative's boss was my regular customer 20 years ago, when he had a small office at Ayer Rajah Crescent. I learnt a lot from him. He was very humble and never had a chip on his shoulder. He would treat his staff very well and his character is good. I don't believe he'd ever do any hanky-panky." It was this regard for the character of Sim that led him to buy stocks of the local tech behemoth.
"I purchased Creative's stock at around $7. When it went up to $38, I sold it off. Then when it went down to $17, I bought some more; those shares I have kept," says Singam, who has an investment portfolio worth $1.1 million. That is quite an achievement for someone who left Malaysia 37 years ago, and arrived in Singapore with just $7 in his pocket………
………Not one to rely on charts, graphs, and price-to-earnings ratios, Singam has a different approach to stock picking. He places a premium on the character of those at the helm, the relative financial stability of the company, and the kind of environment it operates in. And he has a bias for government-linked firms. "I don't like stocks that aren't government backed. Think about how many people depend on the government." Elaborating on some stocks, which he owns, that fit the bill, he says: "Take Comfort Group, for example. They gave me 25,000 shares first and then topped it up to 50,000. When the share price hit $1.32, I sold the shares. And when the price dropped to $0.62, I bought the shares back. I like the company because I work for the company and I know what is going on inside. And Comfort Group has more than 11,000 cab drivers. This is not a company that the government will allow to go bust. How many other companies have this many staff? It's the same with SIA. Look at how many people it employs. And it has paid up for its planes. Very few airline companies can do that."………..
-------------------------
December 26, 2002
This Cabbie's Worth A Million Bucks
G.K. Singam came to Singapore over 30 years ago with just $7 in his pocket. Today, he has an investment portfolio worth $1.1 million. He tells Fundsupermart Magazine where he has put his money to work and what he plans to invest in.
by Bharathi Rajan
Fundsupermart
Jan/Feb 2003 issue
Sim Wong Hoo Was His Regular Customer
In his 20 years as a taxi driver, "Singam" (as he's kn
 own to his colleagues) has driven possibly thousands of passengers. So over the years he has accumulated a wealth of knowledge from the conversations he has had with his customers who come from all walks of life. One of his most memorable encounters was with Creative Technology's Chairman Sim Wong Hoo. "Creative's boss was my regular customer 20 years ago, when he had a small office at Ayer Rajah Crescent. I learnt a lot from him. He was very humble and never had a chip on his shoulder. He would treat his staff very well and his character is good. I don't believe he'd ever do any hanky-panky." It was this regard for the character of Sim that led him to buy stocks of the local tech behemoth.
"I purchased Creative's stock at around $7. When it went up to $38, I sold it off. Then when it went down to $17, I bought some more; those shares I have kept," says Singam, who has an investment portfolio worth $1.1 million. That is quite an achievement for someone who left Malaysia 37 years ago, and arrived in Singapore with just $7 in his pocket………
………Not one to rely on charts, graphs, and price-to-earnings ratios, Singam has a different approach to stock picking. He places a premium on the character of those at the helm, the relative financial stability of the company, and the kind of environment it operates in. And he has a bias for government-linked firms. "I don't like stocks that aren't government backed. Think about how many people depend on the government." Elaborating on some stocks, which he owns, that fit the bill, he says: "Take Comfort Group, for example. They gave me 25,000 shares first and then topped it up to 50,000. When the share price hit $1.32, I sold the shares. And when the price dropped to $0.62, I bought the shares back. I like the company because I work for the company and I know what is going on inside. And Comfort Group has more than 11,000 cab drivers. This is not a company that the government will allow to go bust. How many other companies have this many staff? It's the same with SIA. Look at how many people it employs. And it has paid up for its planes. Very few airline companies can do that."………..
-------------------
So I hope that you will be inspired by this success story. This is not a success story of a man far away in America, but a simple man who is here right on this little island. He probably didn’t realise that what he has been doing (or his approach) is exactly the teaching of Warren Buffett.
So I hope that you will be inspired by this success story. This is not a success story of a man far away in America, but a simple man who is here right on this little island. He probably didn’t realise that what he has been doing (or his approach) is exactly the teaching of Warren Buffett.
Thursday, August 30, 2007
How To Evaluate A Company's Business (Part I)
Correct Mindset of Stock Investment
If you ask around the meaning of buying stocks, most of the people will tell you that it is about buying stock at a cheap price and sell when the price gone up. And don’t be surprised that such answer may also come out from those so-called “financial consultants”.
Now, please, the answer is not wrong, but indicates that these people are treating stock investments like “buying a piece of paper (or record since we are scripless now) and sell it when the price of that paper went up”. If you use this approach or having such mindset, you are not a value investor and you are largely affected by market sentiment. You are just another player.
This is certainly not the Warren Buffett or Peter Lynch’s way. So what is the Warren Buffett or Peter Lynch’s approach? When you buy a company’s shares, you are effectively investing in that company’s business. And you should behave likewise. It is not uncommon to find share price of a company moves (appreciates/depreciates in paper value) in opposite direction against its business. If you focus on the paper, you may cut loss. But if you focus on the business, assuming good fundamental, you will pump in more funds. If you really follow market sentiment and dump a company's share even when it has wonderful business, I felt sorry for you.
So how does a person behave if he/she is considering a partnership business? Let’s say someone invites you to invest in his business. Perhaps the business needs more fund to expand. I am very sure you will do at least all of the followings (list not exhaustive):
- Visit the company, talk to the employees.
- Observe the crowd and look at company’s customers’ record to identify repeated customers.
- Ascertain the company’s SWOP (strength, weakness, opportunity and threat). E.g. customers’ loyalty, strategic location, brand name, market share, cost structure, market competition etc.
- Obtain a copy of business profile.
- Review the company's P&L for last few years. Of course, if the report is not audited, then you have to take with a pinch of salt.
- Have a discussion with the founder. Get him to reveal SWOP and ascertain his integrity. If you found out that he is trying to avoid or covering up something, you should pack up.
I am never a businessman, but I would do at least all of the above. It's really common sense, although my lecturer used to say that "common sense is the least common human attribute". Anyway, if you just want to “trade the paper”, then this article will be irrelevant to you. Now, Warren Buffett and Peter Lynch are real expert when it comes to evaluating a company’s business and its management team. Even though we may just buy only 0.01% of the company’s shares, it should not stop us from using their approach. If time is what you don’t have, then I have a suggestion - pay me and I’ll do it for you.
A True Testimony – Creative Technology
If I remember correctly, a few years ago, an article appeared in the Fundsupermart.com about a Singapore taxi-driver whose investment turned him into a millionaire. If I can find that article again, I will put it on my blog. What happened was one day, this taxi-driver pick up Mr Sim (COE, Creative Technology). Singaporeans should know this man, a poly-grad who turned a company into one with large global market share and dual listing in Nasdaq (likely to be delisted from Nasdaq this month) and SGX. Both of them had a wonderful conversation during the rides and this tax-driver was deeply impressed with his humble customer. One thing for sure, the tax-driver is not an investment analyst, and most probably not a CFA charterholder. But he based on one simply principle that have been highlighted by Warren Buffett over and over again – you invest in a company that is run by a CEO of a such character that you want to marry your daughter to him. The taxi-driver and Mr. Sim's chit-chat session was not long, and the investment decision may look hasty, but that’s not my point.
For those who have been active in local stock market for last 10 years should know that Creative Technology’s share went up from about US$5 a share to nearly US$70 a share in late 90s. That taxi-driver must have invested more than S$100,000 in Creative Technology based on one man’s character. One more highlight, Creative Technology's share price has dropped to near all time low right now due to continuous disappointed earnings. But again, that's not my point.
How To Evaluate A Business?
Firstly, we must accept that our evaluation will be much simpler as compared to Warren Buffett or fund managers. If you tried to do exactly what they are doing, I am afraid that is not going to be possible. You don’t believe? Ok, try to make an appointment with a listed company’s investment relation manager and tell him that you intended to buy 10 lots but you like to interview him first. There are a few reasons why we (retail investors) just can’t be as complete or receive as much information as we want compare to fund managers. For example:
- Warren Buffett buys a controlling stake in a company. Fund managers may not buy controlling stake but the size would be large. Retailers? Ten lots, may be twenty or more. Therefore, you will receive different treatment from the company’s management.
- Information that a company is willing to reveal is likely to be different between meeting Warren Buffett, a fund manager or investing public.
- You can be sure that warren Buffett and fund managers have sophisticated systems/sources to assist them in their evaluation. Retailers? We can’t even afford wirenews at home.
The good news is that there are other things we can do to compensate our shortcomings:
1) Be vigilant
Keep an open eye when you go shopping. Don’t just get entertained, you may make big bucks just by being observance. Let me share a living example. A few years ago, Jurong Point (JP) was not as big as it is today. When JP officially opened for business, I thought the shopping mall will not be impressive. This is because its customers will make up of mainly factory workers, and may probably damage its image. Subsequently, I witnessed how JP grew and expanded its floor area by enlarging the shopping mall. Today, even with its expanded underground carpark, finding a parking lot requires huge amount of luck. Besides the parking lot, finding a seat at the food court “Kopitiam” also requires luck and patience most of the time. There was never an empty space/shop inside JP. Without talking to the management, what I seen with my own eyes is more than enough for me (and my friends) to call a buy on JP (jointly owned by Lee Kim Tah and Guthrie). And true enough, both Lee Kim Tah and Guthrie reported continued rental growth from JP. We made some profit out of it.
2) Take note of aunties’ and uncles’ gossips.
How many times have you heard friends and colleagues commenting or cursing a product or a company vigorously? So what do you do with it? You join in the fun and then you forget about it? Well I don’t. If a few persons said it, it may not be true. But what if you heard again and again from different mix or locations? Then there could be some truth in it. When Breadtalk was listed in 2003, its share price surged more than 50%. Their business concept was quite innovative and fashionable, and many people like it. And I heard the following gossips frequently:
“wah, Breadtalk employ many young girls….”
“eh, that spicy bah hoo (flosss) bread is really nice…..”
I patronized a few of their outlets. I found that the above two statements were true. The bread is nice to eat, but every outlet is heavily staffed. Labour costs would be big problem in a competitive market where you can find many other popular confectioneries such as Bangawan Solo, Four Leaves, Prima Deli etc. In addition, most outlets are located at pime areas, so rental expense will be scary. And after we monitored and study their progress, we decided that Breadtalk should be avoided. Why were we interested in Breadtalk then? Answer - their franchise business. A franchise business model is a wonderful model which had created empires such as MacDonald and 7-11. I knew this long ago but Breadtalk’s progress was not exciting at all. Thus I was unable to differentiate Breadtalk’s business as compared to the rest. There was no reason at all to invest in Breadtalk then. One of my friend (Mr Philip Comd) said this to me:
“By the time their franchise business become successful, the share price would have gone up”.
I replied that it may, but still the important question is whether that “gone up” price is under or over-valued relative to its growth! Price by itself means nothing. It has to be compared against something else. This means that I will invest if my analysis shows a change in Breadtalk's fundamental, and Mr. Market might missed it. It happens many times. We cannot invest base on hope or luck just like visiting a casino.
In Dec 2006.....
To be continue……...
Subscribe to:
Posts (Atom)
Life at NUS-CMC, and still happening......

Visit www.moblyng.com to make your own!